For a shop owner in Johannesburg who is waiting on a loan to expand, the next move by the South African Reserve Bank could change the cost of that money overnight.
The SARB’s Monetary Policy Committee (MPC) meets at 15h00 on 23 September to decide on the repo rate, the rate at which commercial banks borrow from the central bank. A change is measured in basis points, where one basis point equals one hundredth of a percent.
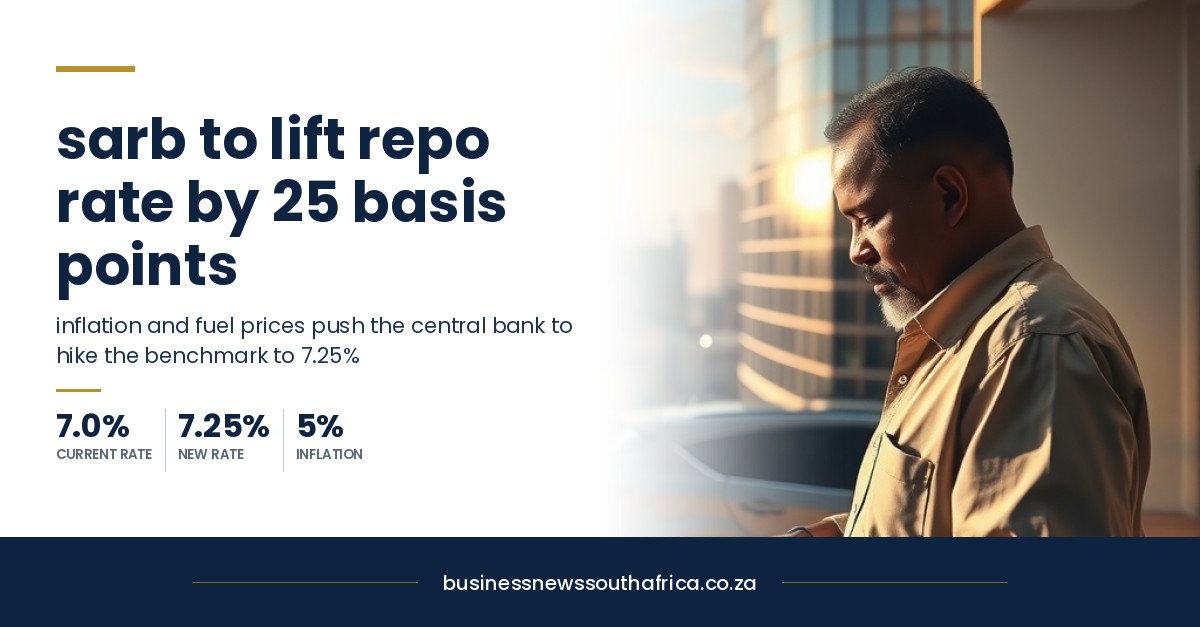
Market participants are betting on a 25-basis-point increase, taking the repo rate from 7.0% to 7.25%. The consensus reflects rising inflation, record-high fuel prices and a recent 25-basis-point hike by the US Federal Reserve. Most banks and analysts, including Investec, Nedbank and Anchor Capital, have signalled a hike.
Mike van der Westhuizen, portfolio manager at CAM Asset Management, is an outlier. He says the decision is “effectively a coin toss” and leans toward a hold, arguing that the MPC may look through short-term price spikes. His view is that any increase is likely to be postponed until the November meeting.
South Africa’s economy adds pressure. Unemployment sits at 33.6%, second-quarter GDP fell 0.2% and inflation for August is expected to hit 5% according to Stats SA. Global oil is around $100 a barrel and the war in Iran keeps supplies tight. The interest-rate gap with the United States has narrowed to about 275 basis points, a factor that could weigh on the rand.
For SMEs, a 25-basis-point hike means higher interest on existing variable-rate loans and tighter credit conditions. A R1 million loan at 7% would see monthly repayments rise by roughly R2 000. Companies may need to revisit pricing, delay expansion plans or lock in fixed-rate financing before the change.
The MPC’s verdict will be released at 15h00. Until then, businesses should monitor the announcement and be ready to adjust cash-flow forecasts. Read more in our Markets & Finance coverage.
In South Africa the repo rate is the benchmark that feeds through to the prime rate set by each commercial bank. When the SARB adjusts the repo rate, banks typically revise their prime rates within a few days, and that change is reflected in the interest charged on most retail and SME loans. The transmission mechanism is monitored by the Financial Sector Conduct Authority, which publishes regular reports on the lag between policy moves and retail pricing. Understanding this chain helps business owners anticipate how quickly a policy shift will affect their borrowing costs and plan accordingly.
Historically, the SARB has used incremental 25-basis-point moves to steer inflation without shocking the economy. Over the past decade, most rate changes have been announced at the MPC meeting and implemented within the same week, giving firms a short window to lock in rates before the new pricing takes effect. This pattern means that businesses often scramble to negotiate fixed-rate facilities in the days leading up to a meeting. Knowing the typical timing can help owners align loan applications with the expected policy outcome.
For companies that rely on variable-rate overdrafts, a rate hike can also raise the cost of working-capital facilities. The central bank’s policy rate influences the cost of funds for banks, which in turn adjust the margin they charge on overdrafts and revolving credit. In practice, a 25-basis-point increase may add roughly 0.2 to 0.3 percentage points to the effective rate on these facilities. Managers should therefore review overdraft usage and consider alternative financing, such as term loans or supplier credit, to mitigate the impact.
SMEs that have not yet secured financing may find that tighter credit conditions accompany a rate rise. Banks tend to tighten underwriting standards when borrowing costs climb, requiring higher collateral or more stringent cash-flow tests. The South African Bankers Association regularly publishes data on loan approval rates, showing a dip after each rate increase. Entrepreneurs should therefore prepare stronger financial statements, maintain higher liquidity buffers, and explore non-bank lenders or development finance institutions as supplementary sources.
The exchange-rate link between the rand and the US dollar adds another layer of complexity. When the interest-rate differential narrows, capital flows can shift, putting pressure on the rand and potentially raising import costs for businesses that source goods abroad. Companies with foreign-currency exposure often use forward contracts or options to hedge this risk, but the cost of such hedges can rise when the rand weakens. Monitoring the rand’s movement after the MPC decision can help firms decide whether to adjust pricing or renegotiate supplier terms.
Looking ahead, the next MPC meeting in November will provide a second data point for businesses to gauge the trajectory of monetary policy. Analysts typically compare the actual rate change with the market consensus to assess the central bank’s stance on inflation and growth. If the September decision aligns with expectations, the November meeting may focus on the durability of inflation pressures rather than further hikes. Business owners should keep an eye on upcoming inflation reports, fuel price trends, and the SARB’s own inflation forecasts to anticipate any further adjustments.