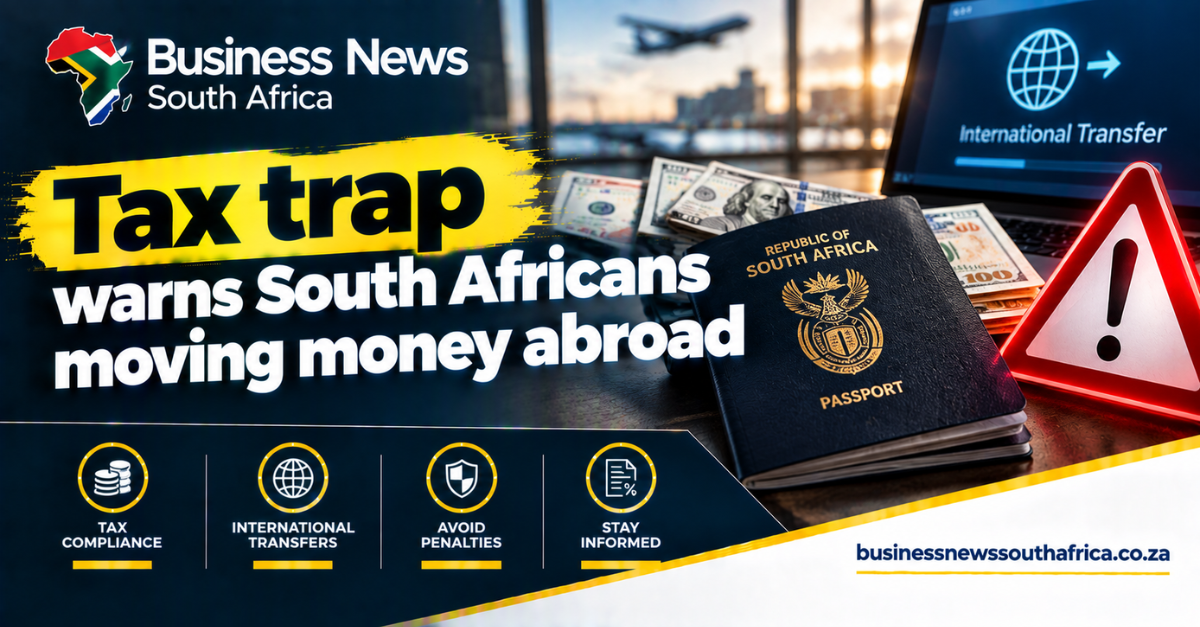
When a Johannesburg property investor signs the final paperwork for a sale and prepares to wire the proceeds to a bank account in Dubai, the last thing on his mind is a tax surprise. Yet the Daily Investor story titled “Tax trap for South Africans taking money out of the country” warns that such transfers can land taxpayers in a fiscal snare.
The article notes that South Africans who move funds overseas may be hit by capital gains tax (CGT) on the appreciation of assets, even if the cash never returns home. Capital gains tax is a levy on the profit made when an asset, such as a property, is sold. The tax is calculated on the difference between the sale price and the original purchase cost, after allowable deductions.
In addition, the piece highlights exchange control rules enforced by the South African Reserve Bank (SARB). Exchange controls are limits on the amount of foreign currency that can leave the country without prior approval. Breaching these limits can attract penalties, which the article describes as a “tax trap” because they often appear as a surprise on a taxpayer’s return.
According to the Daily Investor report, the South African Revenue Service (SARS) treats foreign-sourced income, such as rental receipts or interest earned abroad, as taxable in South Africa, unless a double-taxation agreement (DTA) applies. A DTA is a treaty between two countries that prevents the same income from being taxed twice.
For property owners, the practical implication is that the moment they convert a local sale into a foreign currency transfer, they may need to declare the transaction, calculate any CGT due, and ensure they are compliant with SARB’s exchange-control limits. Failure to do so can result in a tax assessment, interest on the unpaid amount, and possible penalties.
The article does not provide exact figures for how many South Africans have been caught in this situation, nor does it quote a specific SARS official. It does, however, cite the general guidance that the tax authority has issued in recent years, urging taxpayers to seek professional advice before moving large sums abroad.
What remains unclear from the source is whether the tax trap applies uniformly across all types of foreign transfers, for example, whether a simple personal remittance is treated the same as a corporate investment outflow. The Daily Investor piece suggests that the risk is higher for sizeable, one-off transfers linked to asset sales, but it does not quantify the threshold.
In the broader property market, this warning arrives at a time when many South African investors are looking overseas for diversification. The South African property sector has seen a modest slowdown in transaction volumes, prompting some owners to explore foreign markets for better yields. The tax considerations outlined in the article could therefore influence decisions about where to park proceeds from a local sale.
For small-to-medium enterprises (SMEs) that own rental properties, the message is clear: before wiring cash abroad, engage a tax adviser who can map out the CGT liability, check exchange-control compliance, and verify whether a DTA can mitigate double taxation. Ignoring these steps may turn a profitable sale into a costly tax bill.
In short, the Daily Investor’s alert is a reminder that moving money out of South Africa is not just a banking exercise, it is a tax event that can have lasting financial consequences.
South African tax residents remain liable for tax on their worldwide income even after moving funds offshore, and the South African Revenue Service has increasingly focused compliance efforts on cross-border transfers as a way to identify undeclared income or assets. Individuals moving money abroad must typically obtain a tax clearance certificate confirming their affairs are in order, and are subject to an annual single discretionary allowance as well as a larger foreign investment allowance that requires SARS approval before funds can be moved. Failing to follow the correct process, or misunderstanding which allowance applies, can trigger exchange control penalties or a SARS audit well after the transfer has already taken place. SARS’ own guidance on cross-border tax compliance sets out the current allowances and clearance requirements. For related coverage, see this site’s Regulatory and Policy coverage.