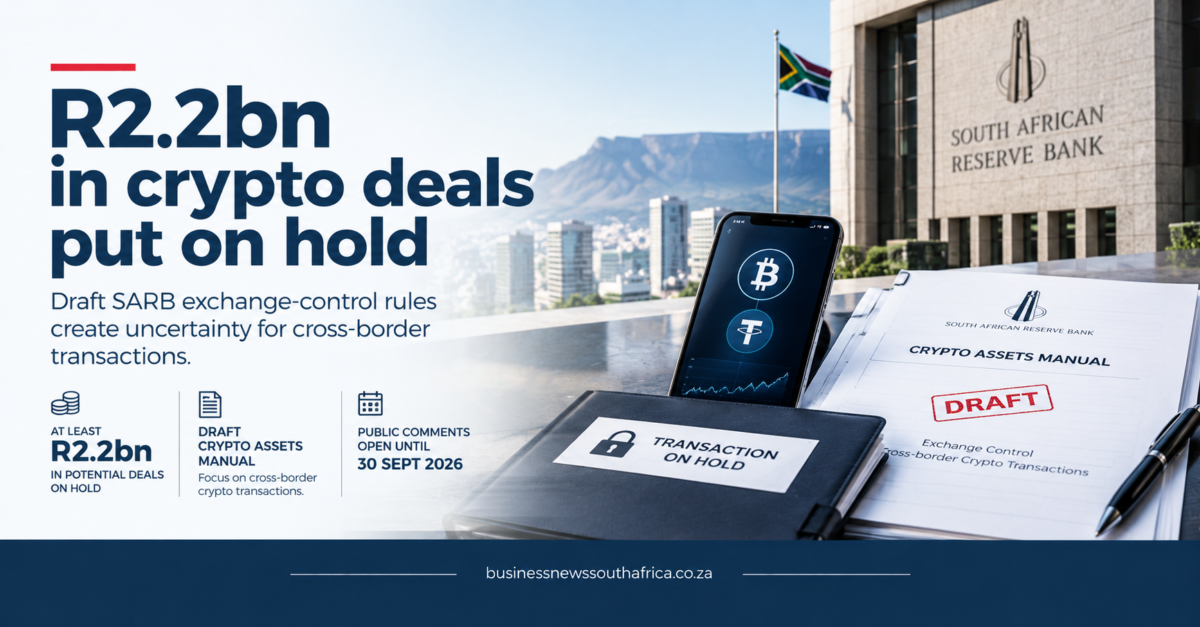
South African crypto companies have paused at least R2.2 billion worth of deals since the South African Reserve Bank (SARB) and National Treasury published a draft manual on 3 August 2026 that would, for the first time, bring cross-border crypto transactions under the country’s formal exchange control regime. The rules are not yet final, they are still open for public comment, but the businesses affected are not waiting to find out whether they survive that process unchanged.
The draft Crypto Asset Manual for Cross-Border Activities is issued under the Currency and Exchanges Act of 1933 and the Exchange Control Regulations of 1961, decades-old legislation now being extended to cover an asset class that did not exist when either was written. Under the proposed rules, resident companies, corporate treasuries and trusts would be barred entirely from cross-border crypto transactions. Only individuals could move crypto offshore, and only within their existing annual Single Discretionary Allowance (R2 million) and Foreign Capital Allowance (R10 million), the same limits that already apply to moving ordinary money out of the country.
Why this matters beyond crypto-native businesses
The practical effect reaches further than the crypto sector itself. South African businesses, and multinational subsidiaries operating across the continent, have increasingly used stablecoins to repatriate profits, pay regional dividends, and route around hard-currency shortages in other African markets where the rand or dollar is scarce. A corporate ban on cross-border crypto transactions removes that option specifically for the entities that most needed a workaround, companies, not individuals moving personal savings.
For Authorised Crypto Asset Service Providers (CASPs) that would still be permitted to facilitate cross-border transfers, the draft manual sets out a three-tier authorisation system. The strictest tier limits remittances to R5,000 a day and R25,000 a month. Providers must hold a minimum of R5 million in unimpaired capital, maintain a physical local presence, and run full customer due diligence under the Financial Intelligence Centre Act, compliance costs that will likely push some smaller providers out of the cross-border market entirely.
The court case that gave the rules their teeth
The regulatory push follows a June 2026 Johannesburg High Court ruling in Mangundhla and Another v South African Reserve Bank, which found that Bitcoin qualifies as both ‘money’ and ‘capital’ for the purposes of South Africa’s exchange control framework. That finding matters because it settles, at least for now, a question that had left crypto’s legal status genuinely ambiguous: whether decades-old currency and exchange legislation actually reaches a digital asset that is not currency in any conventional sense. The SARB has separately maintained, via Joint Communication 1 of 2026, that crypto assets are not legal tender and do not constitute money for domestic payment purposes, a position that sits in some tension with a court finding that crypto is money for exchange control purposes specifically. That contradiction, regulated heavily leaving the country, denied legal status staying inside it, is not a drafting accident so much as two different pieces of law answering two different questions, but it leaves businesses navigating a genuinely unsettled area.
What South African businesses should actually do now
Businesses with any cross-border crypto exposure, whether direct trading, treasury management, or supplier and dividend payments routed through stablecoins, should treat the draft manual as the likely direction of travel even while it remains open for comment, rather than waiting for a final version before reviewing exposure. The public comment period is the only formal opportunity to flag specific operational harms before the rules are finalised, and industry bodies have already warned that overly broad restrictions could push legitimate activity offshore into jurisdictions with looser oversight, precisely the outcome exchange controls are meant to prevent.
For businesses that are not crypto-native but have used stablecoin payments opportunistically to solve a specific cross-border friction, now is the time to map exactly which of those transactions would fall under the corporate prohibition, and what the conventional foreign-exchange alternative would cost in comparison. A workaround that only exists in a regulatory grey area is not a foundation to keep building a payment process on.