“It is difficult to determine the ‘largest’ bank in South Africa, as there are numerous metrics that one can use,” a comparison published by BusinessTech on 22 September put it, and the underlying numbers back that up: each of South Africa’s big five banks leads on a genuinely different measure, and each bank also reports on a different date, so no single snapshot captures all five at once. Here is what each one actually leads on, and what a business owner should take from that.
By market capitalisation: FirstRand, R530.3 billion (30 June 2026)
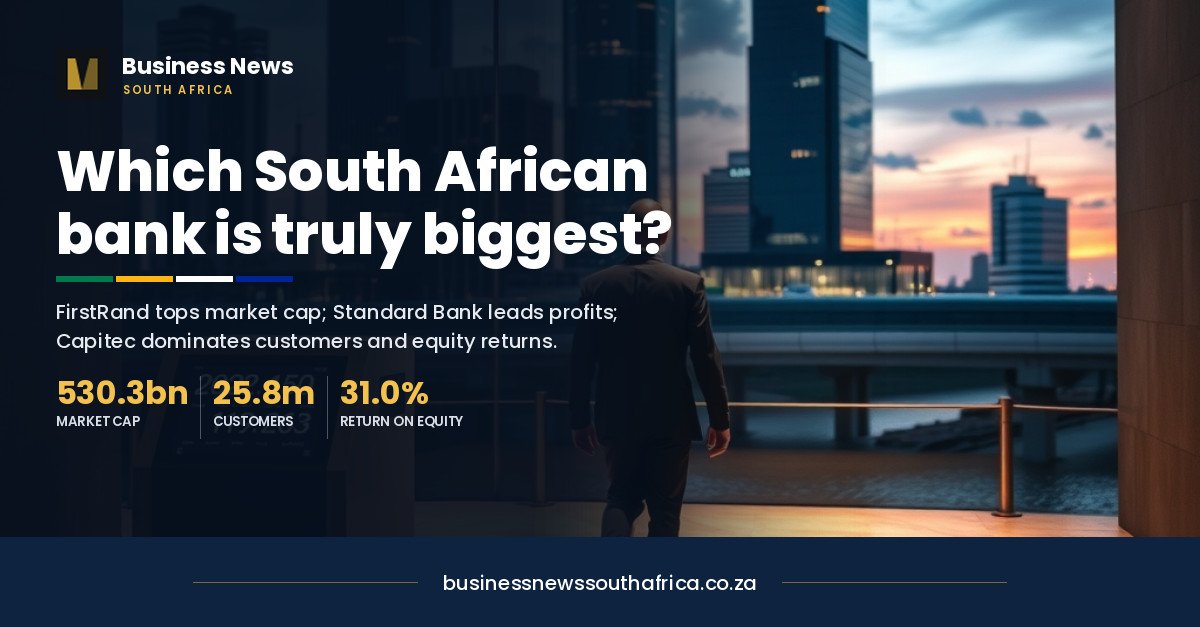
FirstRand, the JSE-listed group behind FNB, is the most valuable of the five by market capitalisation, at R530.3 billion as of its 30 June 2026 half-year mark, with 10.3 million South African customers and a 20.3% return on equity. This is a genuinely dynamic ranking, not a settled one: Standard Bank briefly overtook both Capitec and FirstRand in May 2026 to become Africa’s most valuable bank at R517 billion, the first time all three crossed R500 billion simultaneously, before the ranking shifted again by June.
By profit: Standard Bank, R49.2 billion headline earnings (31 December 2025)
Standard Bank Group, Africa’s largest bank by assets with continent-wide operations well beyond South Africa, reported R49.2 billion in headline earnings for the year to 31 December 2025, nearly double the next closest competitor on this list and a clear reflection of its scale advantage as a genuinely pan-African, not just South African, banking group.
By customer numbers and returns: Capitec, 25.8 million customers, 31% return on equity
Capitec is the clear leader on two different measures at once: 25.8 million South African customers, more than double its nearest rival, and a 31.0% return on equity, the highest of the five by a wide margin, as of its 28 February 2026 results. Built around a low-fee, digitally-led retail banking model, Capitec has converted sheer customer volume into the most efficient profit engine of the five, at least by this measure.
Absa and Nedbank: smaller by scale, still core to SA business banking
Absa Group reported R197.4 billion in market capitalisation and R24.8 billion in headline earnings for the year to 31 December 2025, with 13.1 million South African customers and a 15.0% return on equity. Nedbank, the smallest of the five on market cap at R140.4 billion, reported R17.2 billion in headline earnings and a 15.4% return on equity over the same period, with 8 million customers. Neither competes with the top three on sheer scale, but the sector as a whole reported nearly R150 billion in combined profit for the 2025 financial year, and both remain full-service options for business, corporate and investment banking.
The comparison that actually matters for a business account
| Bank | Market cap | Headline earnings | ROE | SA customers |
|---|---|---|---|---|
| FirstRand (FNB) | R530.3bn | R26.2bn | 20.3% | 10.3m |
| Standard Bank | R511.6bn | R49.2bn | 19.3% | 12.1m |
| Capitec | R521.7bn | R16.8bn | 31.0% | 25.8m |
| Absa | R197.4bn | R24.8bn | 15.0% | 13.1m |
| Nedbank | R140.4bn | R17.2bn | 15.4% | 8.0m |
Each bank’s own most recent report as of the dates above; figures are not from the same calendar date and should not be read as a single simultaneous snapshot.
None of these numbers, on their own, tells a business owner which bank to actually use. Return on equity and profit describe the bank’s own business, not what it will charge a client for a business account, a POS device or an overdraft facility. Our Loan Cost Comparison and Equity vs Debt Calculator tools are built for the actual decision an SME owner faces: what a specific facility from a specific lender will really cost, not which bank happens to be biggest this quarter.