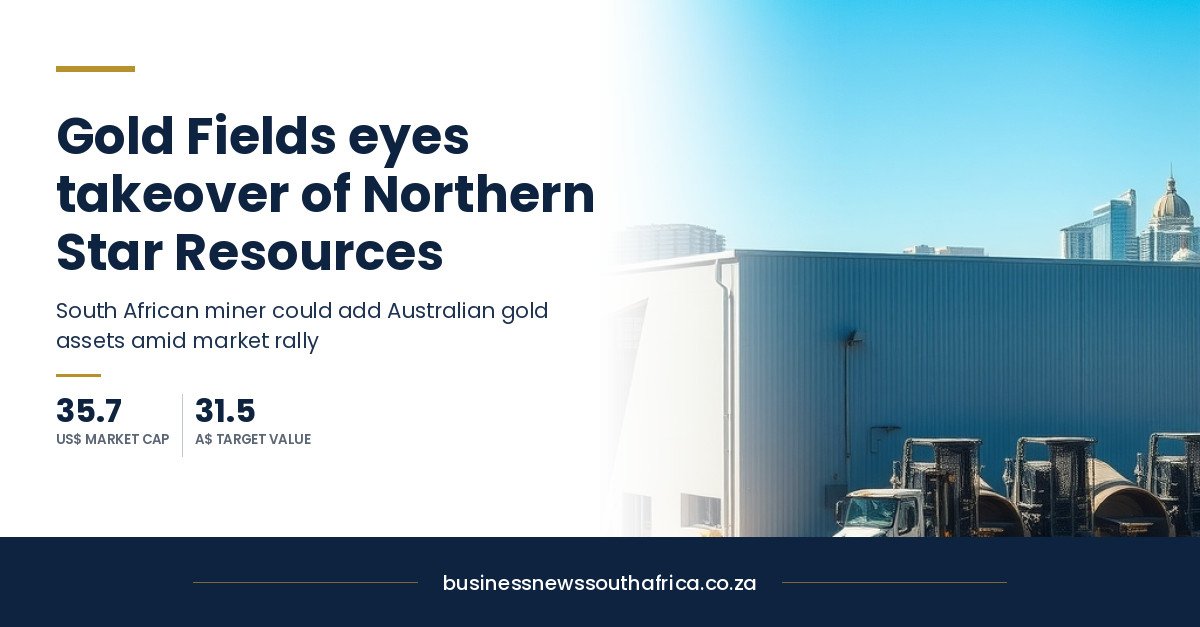
Moneyweb reports that Gold Fields has approached Northern Star Resources about a possible acquisition. The South African miner, whose market capitalisation is about US$35.7 billion, would be looking at a target valued at roughly A$31.5 billion (US$22.1 billion). The information comes from people with knowledge of the matter who asked to remain anonymous.
Why the deal matters
A takeover, or acquisition, means one company buys enough shares to control the other. For Gold Fields, adding Northern Star would deepen its exposure to Australia’s prolific gold deposits and could create a larger, more diversified portfolio that spans Africa, the Americas and Australia. The move follows Gold Fields’ recent purchases of Gold Road Resources and Osisko Mining, signalling a strategy of growth through acquisition.
Gold prices have been on a multi-year rally, prompting many miners to look for ways to boost returns on existing assets. A larger combined entity could achieve economies of scale, negotiate better contracts with suppliers and spread the cost of capital across a broader asset base. For South African suppliers, contractors and service firms that already work with Gold Fields, a bigger operation could mean more stable demand for equipment, logistics and technical services.
Northern Star, based in a Perth suburb, has been under pressure from activist investor Elliott Investment Management. Elliott has urged the company to consider a sale or asset divestments and has called for changes to the board. The miner appointed a new chief executive officer in July, but production guidance has been cut repeatedly this year because of problems at its Kalgoorlie processing plant.
While the interest is confirmed by sources, the exact price, financing structure and regulatory timeline remain unknown. Any deal would need approval from Australian and South African competition authorities, and shareholders of both companies would have to vote on the terms.
For small-business owners in the mining supply chain, the key takeaway is to watch how gold price trends and consolidation activity affect contract opportunities. A larger miner may prefer long-term supply agreements, which could provide more predictable revenue streams for local vendors. Keeping an eye on the outcome of this potential deal can help SMEs position themselves for future procurement cycles.
Read more about similar market moves in our Markets & Finance coverage.
Moneyweb reported that Northern Star’s shares have slipped 17% in Sydney trading this year, leaving the company with a market value of A$31.5 billion. By contrast, Gold Fields has fallen about 9% over the same period, maintaining a market capitalisation of US$35.7 billion. The divergence in share performance underscores the differing investor sentiment toward each miner, with the South African group appearing more resilient despite the broader market dip. The price gap could give Gold Fields negotiating leverage if it proceeds, while the decline also means any offer would need to convince Northern Star shareholders that the premium justifies the loss of recent value.
Moneyweb reported that Northern Star chair Michael Chaney disclosed in a letter to shareholders that the company had been approached by several suitors over the past year, but he argued the timing was not right for a sale. This admission signals that the board is already fielding interest, which may influence how aggressively Gold Fields structures its proposal. The presence of multiple potential buyers can drive up the valuation, forcing Gold Fields to consider a higher cash component or more attractive share-exchange terms to win over the board and shareholders.
Moneyweb reported that the activist investor Elliott Investment Management has repeatedly urged Northern Star to explore a sale or asset divestments and has called for an overhaul of the board. Elliott’s pressure adds another layer of complexity, as any offer must address the hedge fund’s expectations for value creation. If Gold Fields can present a clear strategic roadmap that satisfies Elliott’s demand for a higher return, it may reduce resistance from the activist and smooth the path to shareholder approval.
In South Africa, a cross-border acquisition of this size must clear both the Competition Commission and the Australian Competition and Consumer Commission. The process begins with a formal notification, followed by a detailed review of market concentration, potential anti-competitive effects and any public interest concerns. Companies typically submit a draft agreement, financial statements and a competition impact assessment. The regulators then have a set period to either approve, request modifications or block the deal. Delays are common, especially when assets span multiple jurisdictions, so businesses should monitor the timeline for any extensions that could affect contract negotiations.
For South African owners of mining equipment, transport and technical services, the key is to track how the deal shapes procurement policy. A merged entity often consolidates its supplier base, favouring partners that can meet larger volume requirements and longer contract terms. Watching the regulatory filings and shareholder meeting outcomes will reveal whether Gold Fields intends to retain existing contracts or renegotiate them under a new procurement framework. Staying engaged with industry associations and maintaining flexibility in pricing and delivery capabilities will position local firms to benefit from any shift in the supply chain.