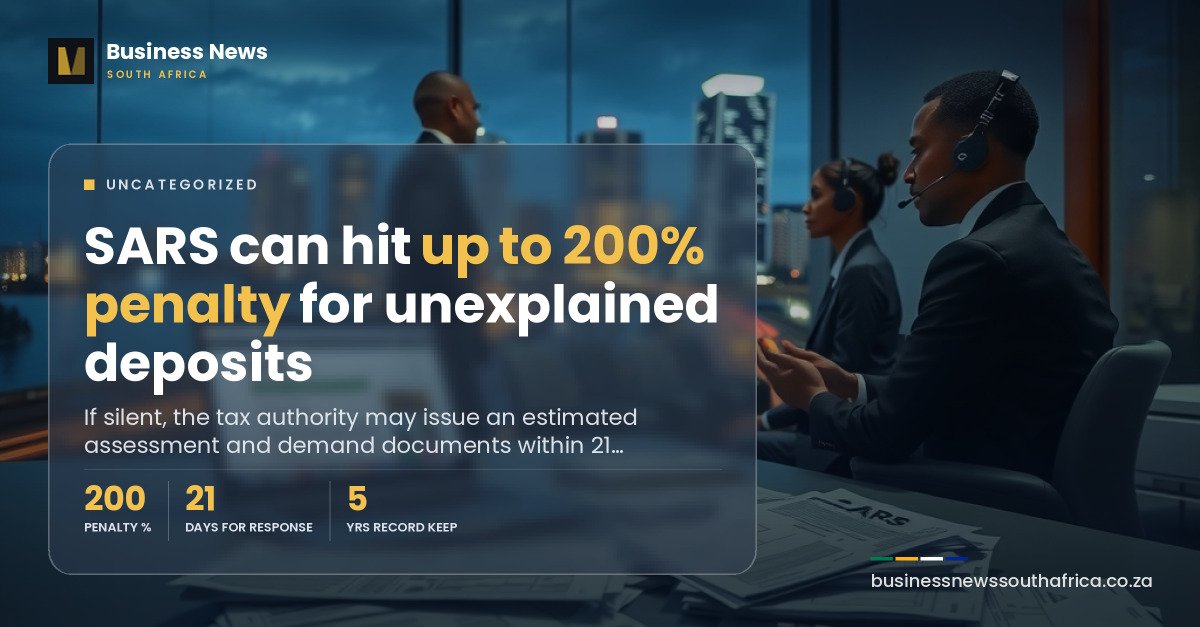
A bank deposit you cannot explain can cost a business owner an estimated assessment and a penalty of up to 200% of the tax involved. On 16 October 2026, IOL News quoted tax consulting manager Lambert Roberts saying SARS may issue an estimated assessment where bank statements show credits that cannot be explained. The law behind that is plain, and owners of sole proprietorships, partnerships and small companies who run personal and business money through the same accounts are the most exposed.
What the warning said, and how SARS selects people
According to Briefly News, which reported the IOL piece, Roberts listed transfers between personal accounts, money from a spouse, loans from friends or family and proceeds from selling personal belongings as deposits SARS could misread. He said a bank credit is not automatically taxable income, but you may have to spend time and money proving that if you cannot document its source. We could not open the IOL article itself, so those points come from Briefly’s report.
SARS says verification means checking your return against third-party data, financial and accounting records and supporting documents, and that it can verify any taxpayer. Section 40 of the Tax Administration Act lets SARS select a person on the basis of any consideration relevant for the proper administration of a tax Act, including a random or risk assessment basis. You need not have done anything wrong to be picked.
Where the bank data comes from
Section 26 allows the Commissioner to require, by public notice, anyone who pays or receives amounts for another person, or otherwise transacts with them, to submit a return. SARS’s third-party data page lists banks, Postbank, estate agents, attorneys and long-term insurers among IT3(b) submitters. The IT3(b) row covers investment, rental, interest and royalty amounts, and transactions recorded in an account maintained for another person, which SARS describes as transactional accounts like bank accounts.
The submission windows are 1 April to 31 May (annual) and 1 September to 31 October (bi-annual), so the current window closes on 31 October. The page does not say every deposit is itemised, so do not assume SARS sees each transfer. Assume it can ask for the statements that show them.
The request for relevant material
When SARS wants proof it uses section 46. It may require a taxpayer to submit relevant material “within a reasonable period”, the material must be described with reasonable specificity, and it must be delivered at the place, in the format and within the time specified in the request. SARS may extend the period if you give reasonable grounds.
The Act fixes no number of days: the deadline is the date on your letter. The 21 business days often quoted is a different clock. SARS says it will attempt to verify within 21 business days after you have uploaded the requested documents. Uploads go through eFiling or the SARS Online Query System, up to 20 documents of 5 MB each, and the letter’s barcode links them to your record.
If you stay silent, section 95(1)(c) lets SARS issue an estimated assessment after more than one request has gone unanswered. You then have 40 business days from the date of assessment to ask for a reduced or additional assessment by submitting the material. Wilfully or negligently failing to furnish requested information is also an offence under section 234(2), punishable by a fine or up to two years in prison.
What the penalties look like
If a deposit proves to be undeclared income, you owe the tax, interest and possibly an understatement penalty under sections 222 and 223. SARS says a penalty can be up to 200% of the shortfall. The standard rates in the section 223 table are:
- Substantial understatement: 10%, defined in section 221 as prejudice above the greater of 5% of the tax properly chargeable or R1 000 000.
- Reasonable care not taken in completing the return: 25%.
- No reasonable grounds for the tax position taken: 50%.
- Gross negligence: 100%. Intentional evasion: 150%.
The rates rise if you are obstructive or it is a repeat case, to as much as 200%. They fall with voluntary disclosure: to 0% for most categories before you are notified of an audit, and 5% for gross negligence and 10% for evasion. The penalty also applies to estimated assessments.
What to do if you mix personal and business money
Section 29 requires records that enable SARS to be satisfied you complied, kept for five years from the date the return is submitted.
- Keep statements for both accounts in every own-account transfer and match them by date, amount and reference, as Roberts advised.
- Keep loan agreements or written proof of the terms and payment trail.
- Keep the invoice behind every customer payment that lands in a personal account.
- If you put your own money into a company, record at the time whether it was a loan or an investment, and ask your accountant how to show it.
- Answer every SARS letter by its date, and ask in writing for more time before it passes.
A separate account makes this easier: see how to open one and separate your finances, and our influencer tax guide for a sole trader’s view of income. TaxTim’s note on verifications and audits adds that SARS strives to give at least 21 business days to respond to an audit findings letter. Confirm the deadline in your own letter and take professional advice before you reply.