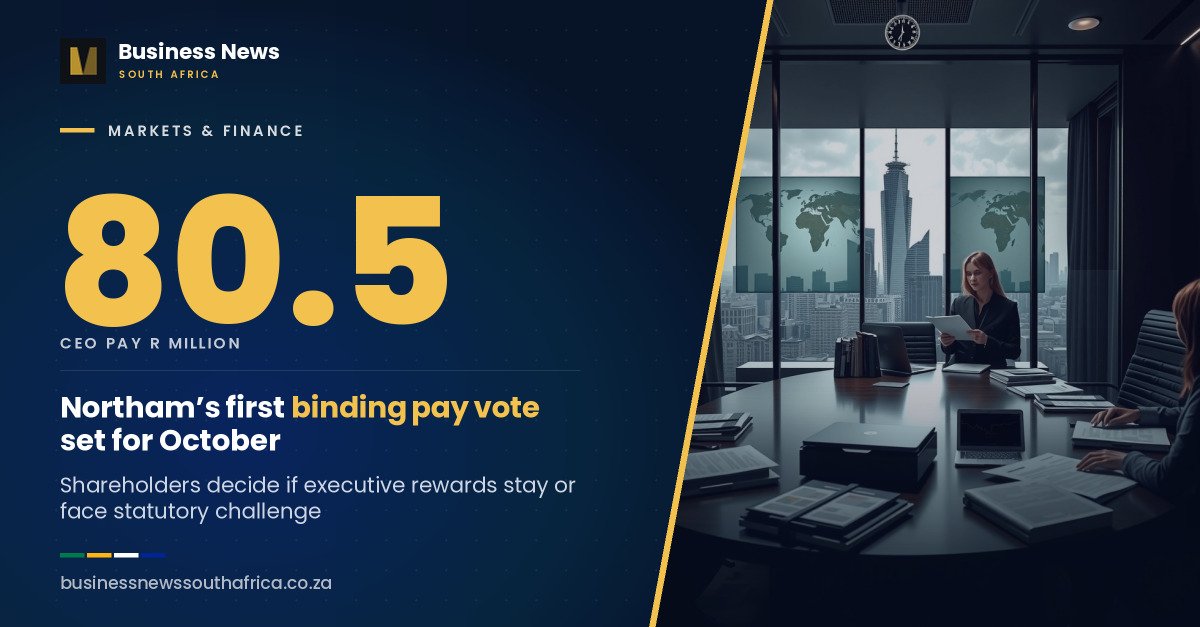
Northam Platinum Holdings shareholders vote on Monday 26 October on how the miner pays its executives, and for the first time the result will bind the board. The annual general meeting, which starts at 10:00 and is held entirely online, puts the company’s remuneration policy and remuneration report to ordinary resolutions that need more than 50% support. The vote follows a decade in which advisory votes on Northam’s pay drew opposition ranging from 10% to 67%, according to a Bloomberg report carried by Mining Weekly.
The notice of meeting changes what a vote means
The mechanics are set out in Northam’s own notice of the 2026 annual general meeting, published with its audited results on 28 August. Resolution 5.1 asks shareholders to approve the group remuneration policy and resolution 5.2 asks them to approve the remuneration report. The notice explains that sections 30A and 30B of the Companies Act, introduced by the Companies Amendment Act of 2024, took effect on 22 May 2026. If resolution 5.1 passes, the policy stays in force for three years unless it is materially amended. If 5.2 passes, shareholders will have approved how the policy was implemented during the year.
The notice adds that the JSE has confirmed compliance with the new sections counts as compliance with its own rules, so Northam no longer has to put non-binding advisory resolutions to shareholders. Until now, a bad vote forced the company to invite dissenting shareholders to write in, then adjust. In future the consequences are statutory. Bloomberg reports that a rejection of resolution 5.2 would not reverse pay already awarded, but would require the remuneration committee to explain at the next AGM how shareholder concerns were addressed, and its members would have to stand for re-election to the committee. The notice itself describes only the effect of approval, so that description of the consequences of a defeat rests on Bloomberg’s account of the amended law.
The record of dissent is Northam’s own
This is not a sudden revolt. Northam’s remuneration report for the year to 30 June 2024 shows the voting results from the two AGMs before it. In 2023, 66.55% of votes were cast against the remuneration policy and 59.87% against the implementation report. In 2022 the figures were 56.48% and 55.99%. Both sets of votes were advisory, and the company said then it was of “great concern” to the committee. It responded by introducing a minimum shareholding requirement for executive directors and replacing contractual change-of-control lump sums with an upfront award of phantom shares.
Northam told Bloomberg the policy and implementation reports were approved by a supermajority last year after extensive consultation, and that it is “guided by the supermajority of its shareholders and not by the ISS recommendations.” We have not seen the 2025 vote percentages in the documents reviewed, so that supermajority claim is the company’s own.
What the proxy advisers and investors are saying
According to Bloomberg, Institutional Shareholder Services describes the approach as “overly generous” and has recommended clients vote for the policy but against the remuneration report, for at least the fifth year running. Its stated concern is the share-incentive plan, where a large proportion of awards can vest even if performance targets are missed. Glass Lewis, by contrast, advises approving both resolutions while noting the history of dissent. Two North American public-sector investors, the State Board of Administration of Florida and British Columbia Investment Management Corp, say they will vote against the report. Both hold small stakes. ISS has scrutinised pay at a sector peer too, as we reported when it flagged Impala Platinum executive bonuses.
The pay numbers and the profit behind them
Bloomberg reports that chief executive Paul Dunne was paid R80.5 million in the year ended 30 June 2026 and R223.6 million in 2025. It sets that against Impala Platinum chief executive Nico Muller at R69 million in its 2026 financial year, and Valterra Platinum’s Craig Miller at about R46 million for the year to 31 December 2025. Northam calls the claim that it pays executives more than peers “factually incorrect” and cites a Deloitte benchmarking report which, it says, puts its CEO and CFO at the bottom of the peer group on total remuneration for on-target performance. We could not verify the Deloitte report or the pay figures against a published F2026 remuneration report, so these are attributed to Bloomberg and the company.
The performance side is public. In its 28 August results announcement on SENS, Northam reported sales revenue of R54.0 billion, up 64.1%, operating profit of R14.15 billion against R3.59 billion a year earlier, and headline earnings per share of 3,044.2 cents. It declared a final dividend of 1,000 cents and a total of 1,700 cents for the year, about R6.8 billion in aggregate. We covered those numbers when the audited FY2026 results came out. A fall in the chief executive’s pay alongside a surge in profit is the argument management can make; investors sceptical of the vesting rules will say the question is how pay behaves when targets are missed, not met.
Why it matters beyond Northam
The Northam vote is an early public test of the amended Companies Act in the mining sector. Any listed company with a history of dissent now faces the same consequence of a rejected remuneration report, and boards will read the result closely. The company is also in a sensitive period, having reported an unsolicited approach and launched a strategic review, which Bloomberg says opened it to takeover or asset-sale proposals. Shareholders deciding on pay are also, in effect, deciding how much goodwill the board has while that process runs. For the many South African companies that report pay to the market, including Shoprite, where chief executive pay rose to R117.8 million, the Northam result will show how much weight the new statutory vote carries.
What is still unknown
The outcome. Results are expected on SENS on or about 26 October, and the final tally will show whether the policy and the report are treated differently, as ISS has recommended. It is not clear how many shares have already been voted by proxy, how the larger institutional holders will vote, or whether the board will say what it would change after a defeat. The company has not published a detailed rebuttal to ISS beyond its statement to Bloomberg.