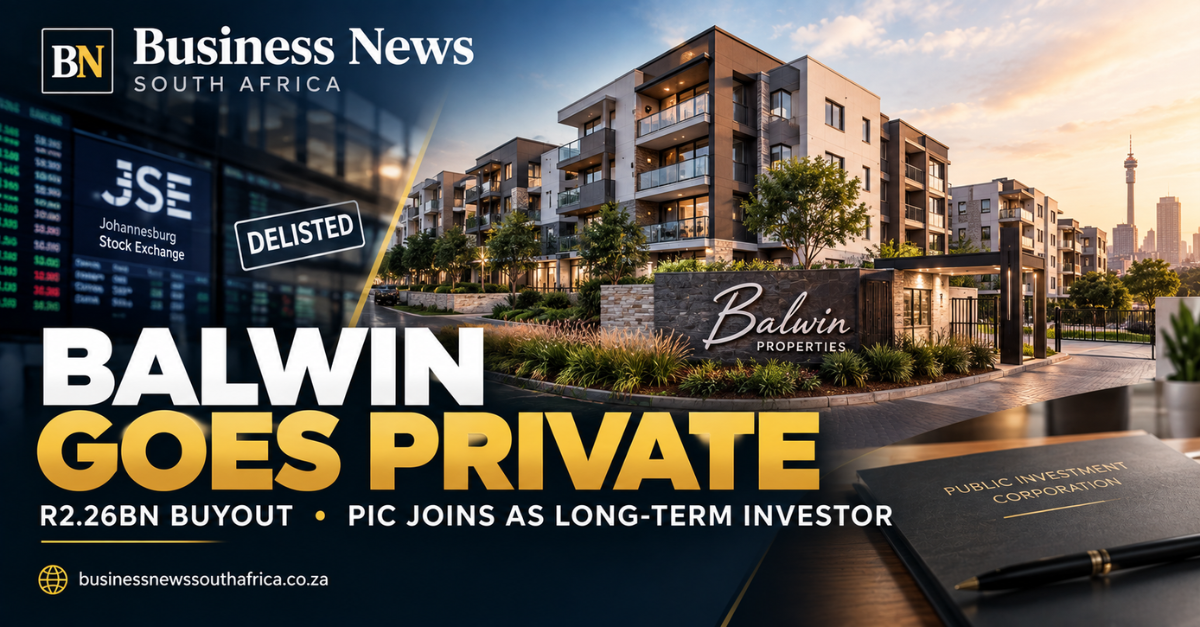
According to Moneyweb, residential developer Balwin Properties has moved from public to private ownership after an 11-year stint on the Johannesburg Stock Exchange (JSE) and three and a half years on A2X Markets. The change follows a take-private scheme of arrangement, a legal process that lets a company buy back its own shares and remove itself from the exchange, valued at R2.26 billion.
For the 98.48% of eligible shareholders who voted in favour, the deal meant a cash payment of R4.35 per share on 21 September 2026. Founder and chief executive officer Steve Brookes, managing director Rodney Gray and the broader executive team will stay on the job, and they are also reinvesting alongside the Public Investment Corporation (PIC), which is acting on behalf of the Government Employees Pension Fund (GEPF). The PIC’s involvement brings long-term institutional capital to the company’s development pipeline.
Balwin’s pipeline currently lists 26 334 build-to-sell apartments across Gauteng, KwaZulu-Natal and the Western Cape, with an additional 7 700 units under review for possible build-to-rent projects. The shift to private ownership does not alter the number of units under construction, but it does change the financing landscape. With the PIC as a permanent shareholder, the developer can tap a stable source of funding without the quarterly earnings pressure that comes from being listed.
Why the move matters to the broader market
For small-to-medium property developers, Balwin’s delisting highlights a growing trend: large, listed developers are opting for private capital structures to secure long-term funding and avoid the volatility of the equity market. The South African residential market has been under pressure from high interest rates and a shortage of affordable housing. Institutional investors such as the PIC are increasingly looking for assets that can deliver steady cash flow, and build-to-rent projects fit that profile.
From a regulatory perspective, the JSE will no longer have Balwin’s governance data on its public filings, but the company says the discipline and accountability gained from its listed years will remain part of its operating model. “Being listed made Balwin a better company. The governance, discipline and accountability that came with being a listed company are now part of the way we operate,” Brookes told investors, according to the source.
For investors, the transaction offers a clear exit route. The PIC’s participation signals confidence in the sector, which could encourage other pension funds to consider similar stakes in residential developers. However, the move also reduces the number of listed residential developers, potentially limiting retail investor exposure to the housing market.
SME owners in related fields, construction contractors, material suppliers and property management firms, may see a steadier flow of work if Balwin’s pipeline proceeds as planned. The private structure could allow the company to make quicker decisions on land acquisition and project design, which can benefit downstream suppliers that rely on timely contracts.
Balwin’s management emphasised continuity. “I founded Balwin 30 years ago and remain as committed to the business today as I was then,” Brookes said. “Our management team remains in place, invested and operationally involved.” The statement underscores that the delisting is not a wholesale overhaul but a strategic shift in capital sourcing.
While the immediate impact on the JSE is modest, the removal of one mid-cap residential developer, the longer-term implications for capital markets and the housing sector are worth watching. The PIC’s long-term stake could set a precedent for other pension funds to back development pipelines directly, rather than through listed equities.
For entrepreneurs looking to raise capital for property projects, the Balwin case illustrates that a strong pipeline and credible management can attract institutional backing without the need for a public listing. The company’s experience also shows that maintaining high governance standards can pay dividends when negotiating private deals.
Balwin’s next steps will involve executing its build-to-sell and build-to-rent programmes, leveraging the PIC’s capital to weather interest-rate headwinds and to meet the ongoing demand for housing across South Africa’s major provinces.