South African families are now shouldering higher debt costs while energy bills and everyday prices keep climbing. The latest move by the South African Reserve Bank (SARB) to raise interest rates adds a new layer of strain to already stretched budgets.
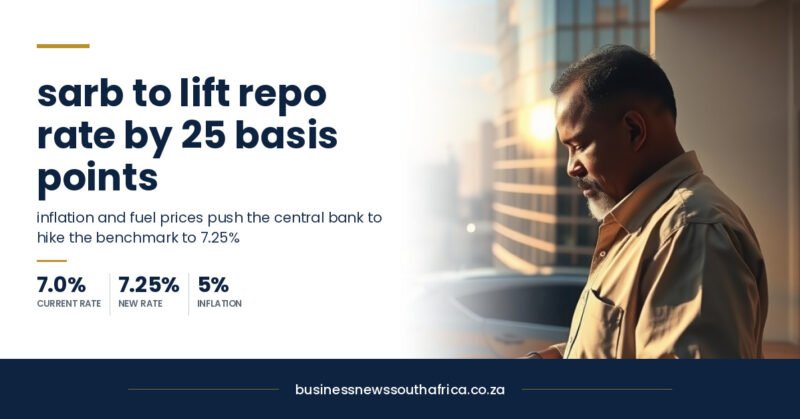
The Monetary Policy Committee (MPC) voted unanimously on 23 September to lift the repo rate, the rate at which banks borrow from the central bank, by 25 basis points to 7.25%. That change automatically pushes commercial banks’ prime lending rate, the benchmark for most consumer loans, to 10.75%, a level not seen since June 2025.
What the hike means for households
Aluma Capital chief economist Frederick Mitchell said the decision “makes little sense in the context of South Africa’s economy” and will punish households. His view is a claim from the economist, not an independently verified fact. Mitchell argues that most of the country’s inflation pressure comes from abroad, higher global fuel prices, a weaker rand and rising import costs, which a higher repo rate cannot curb.
He points out that diesel prices rose in August and petrol and diesel both jumped in September, with October expected to bring record-high pump prices. Because these fuels are priced in dollars, a higher local interest rate does not affect the Brent crude benchmark, global supply bottlenecks, or South Africa’s logistical challenges.
For consumers, the jump to a 10.75% prime rate translates into steeper repayments on mortgages, vehicle finance and credit cards. Every extra rand spent on interest is a rand taken away from household savings and everyday spending.
Businesses feel the pinch too. Mitchell notes that gross fixed capital formation, the money spent on factories, equipment and infrastructure, is already low at about 14-15% of GDP, well below the National Development Plan’s 30% target. Higher financing costs raise the hurdle rate for new projects, discouraging firms from investing in upgrades, mining shafts, renewable energy or logistics expansion.
According to the SARB, raising the policy rate is the only tool it currently has to try to contain inflation. Mitchell warns that without addressing structural impediments, such as electricity tariffs, municipal fees and logistics bottlenecks, monetary tightening will merely shift the burden onto borrowers without easing the underlying price pressures.
For small-business owners and entrepreneurs, the message is clear: tighter credit conditions will make it harder to fund growth, while households will have less disposable income to spend on goods and services. The broader economy may see slower consumption and weaker investment, feeding a cycle of reduced demand.
Read the full commentary on businesstech.co.za. For more on the Reserve Bank’s policy framework, visit the South African Reserve Bank. For related analysis, see our Markets & Finance coverage.
BusinessTech reported that consumers will be paying close to R30 per litre at the pumps in October, adding to the fuel price hikes that began in August for diesel and continued in September for both diesel and petrol. The economist’s warning that these increases will push pump prices to record levels underscores how external, dollar-denominated energy costs are passing straight through to household budgets. Because the rate hike does not affect the Brent crude benchmark, the additional burden on borrowers is purely financial, raising the cost of servicing mortgages, vehicle loans and credit cards. This new fuel price pressure compounds the debt-service shock already created by the prime lending rate moving to 10.75%.
BusinessTech reported that gross fixed capital formation (GFCF) remains stagnant at around 14-15% of GDP, well below the National Development Plan’s target of 30%. The higher financing costs resulting from the 10.75% prime rate raise the hurdle for capital projects, discouraging firms from committing balance-sheet capital to factory upgrades, mining shaft recapitalisation, renewable energy development or commercial logistics expansion. The economist highlighted that without a manageable cost of capital, long-term physical capital formation stalls, limiting productivity gains and job creation. This structural weakness means the economy is less able to absorb the shock of higher borrowing costs, deepening the risk of a prolonged slowdown.
BusinessTech reported that households are already “besieged” by cost pressures that sit above inflation, including municipal tariff hikes, escalating electricity costs and rising food transport margins. While the article does not give exact percentages for these items, the description points to a cumulative effect that erodes disposable income beyond what monetary policy can offset. The combination of higher utility bills and transport costs means that even if borrowing becomes more expensive, the underlying price drivers remain untouched. This dynamic forces consumers to allocate a larger share of their limited resources to essential services, leaving less room for savings or discretionary spending.
In South Africa, the Reserve Bank’s primary tool for curbing inflation is the repo rate, which influences the prime lending rate that banks use for most consumer credit. When the repo rate is raised, commercial banks typically increase their prime rate, making loans more expensive and theoretically dampening demand. For a business owner, higher borrowing costs can delay expansion plans, reduce working-capital availability and increase the cost of inventory financing. The significance lies in the direct link between interest rates and cash flow: tighter credit squeezes both household consumption and corporate investment, which together drive economic growth. Understanding this mechanism helps firms anticipate changes in financing conditions and adjust their budgeting and pricing strategies accordingly.
BusinessTech reported that the Monetary Policy Committee’s next steps will be closely watched, with the October consumer price index release and any subsequent MPC meeting likely to shape future rate moves. Stakeholders should monitor inflation trends, especially in fuel and electricity, as well as any signals from the Reserve Bank about the durability of current price pressures. Watching the evolution of GFCF as a share of GDP will also indicate whether investment is beginning to respond to the higher cost of capital. For small-business owners, keeping an eye on these indicators can inform decisions on debt restructuring, pricing adjustments and timing of capital projects, helping to mitigate the impact of the current monetary tightening.