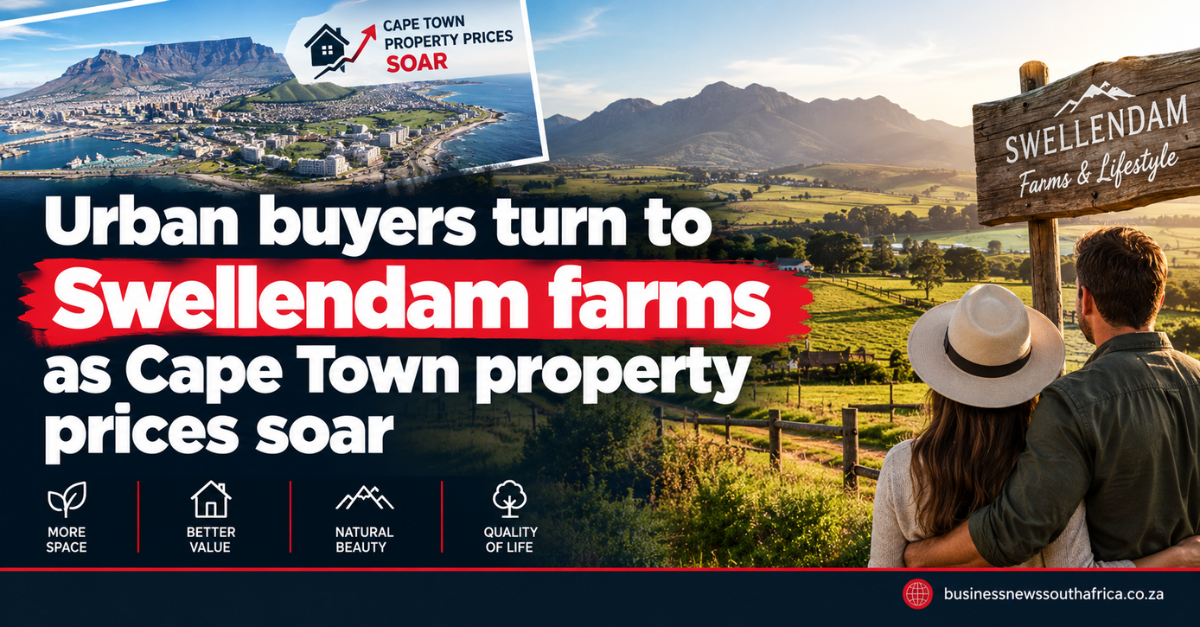
Urban South Africans are increasingly buying lifestyle farms near Swellendam, a 283-year-old town, as an alternative to costly Cape Town homes, according to Seeff Country principal Jaco Badenhorst. The trend, known locally as “semigration”, describes city dwellers, particularly from Gauteng, purchasing second homes or holiday retreats in rural areas while keeping their primary residence in the city.
Semigration has gained momentum as Cape Town’s property market outpaces all other regions. Stats SA’s residential property price index recorded an 11% year-on-year increase for Cape Town in April, the highest rise of any metropolitan area, while the Western Cape overall saw an 11.2% increase, the strongest provincial growth (Stats SA).
Swellendam, founded in 1743 and the third oldest town in South Africa, is attracting attention because it lies roughly three hours’ drive from Cape Town. Its heritage-conscious community has resisted certain modern developments, preserving a rural character that appeals to buyers seeking privacy and open space.
Water security remains a top consideration. The Western Cape endured severe drought between 2015 and 2018, prompting “day zero” fears and causing billions of rands in lost agricultural revenue. Prospective owners therefore prioritise properties with reliable water sources for household use, small-scale farming, orchards or livestock.
Beyond water, buyers value good road access, which reduces the inconvenience of remote locations. Badenhorst notes that many purchasers are opting for farms instead of traditional coastal holiday homes because rising coastal property prices, higher municipal rates and a desire for greater self-sufficiency make rural alternatives financially attractive.
Lifestyle farms also offer the possibility of supplementary income through small-scale agricultural activities, while still providing the leisure benefits of open land, privacy and outdoor recreation.
Financing these properties differs markedly from standard residential mortgages. Most commercial banks treat agricultural land as a specialised asset, applying shorter repayment periods of 10 to 15 years and requiring deposits of up to 50% of the purchase price. Badenhorst advises buyers to engage lenders early and plan their financing carefully to avoid surprises.
For urban residents weighing the switch, the key is to balance the appeal of lower entry costs and a self-sufficient lifestyle against the stricter loan terms and the need for secure water and transport links.
Read more property stories at Business News South Africa, Property.
Beyond Swellendam, buyers are also turning their attention to the Klein Karoo and Montagu, where the blend of scenic valleys and historic towns adds to the appeal of a weekend retreat. The community in Swellendam has historically resisted modern intrusions such as traffic lights and other developments that could compromise its heritage, a stance that resonates with purchasers seeking an authentic rural ambience. This preservation mindset reinforces the market’s perception of the area as a place where tradition and lifestyle intertwine, offering a distinct alternative to the rapid urbanisation seen elsewhere in the Western Cape.
Water security remains a decisive factor, especially given the severe drought that gripped the Western Cape between 2015 and 2018. During that period, restrictions intensified and fears of “day zero” prompted many farms to suffer billions in lost agricultural revenue. Prospective owners therefore scrutinise the reliability of water sources, assessing whether the supply can sustain household needs, orchards, livestock or small-scale farming. Access to a dependable water supply not only safeguards daily living but also underpins the viability of any supplementary agricultural venture on the property.
When it comes to financing, commercial banks classify agricultural land as a specialised asset, which translates into distinct lending criteria. Deposits can reach up to 50 % of the purchase price, and loan terms are typically limited to a ten- to fifteen-year repayment window, shorter than those for conventional homes. Engaging lenders early in the process allows buyers to align their financing structure with these parameters, reducing the risk of unexpected conditions later in the transaction. This approach also gives borrowers time to arrange any additional collateral that banks may require for the specialised nature of the asset.
The conveyancing of a farm follows a sequence that begins with a title deed search to confirm ownership and any existing encumbrances. Buyers must also verify water rights, as these are often tied to the land and can affect both domestic use and agricultural activities. Once the deed is clear, a transfer document is drafted and lodged with the Deeds Office, a step that typically takes several weeks. During this period, municipal rates and road access assessments are finalised, ensuring that the property meets the buyer’s expectations for connectivity and service obligations before settlement.
Owners of lifestyle farms can enjoy amenities that rival those of coastal properties, including expansive open spaces, privacy and opportunities for outdoor recreation. The ability to generate supplementary income through small-scale agricultural activities adds a layer of financial resilience, allowing owners to offset some of the higher upfront costs associated with the specialised financing. This combination of lifestyle benefits and potential earnings makes the farm model an increasingly attractive proposition for urban buyers seeking both leisure and a degree of self-sufficiency.