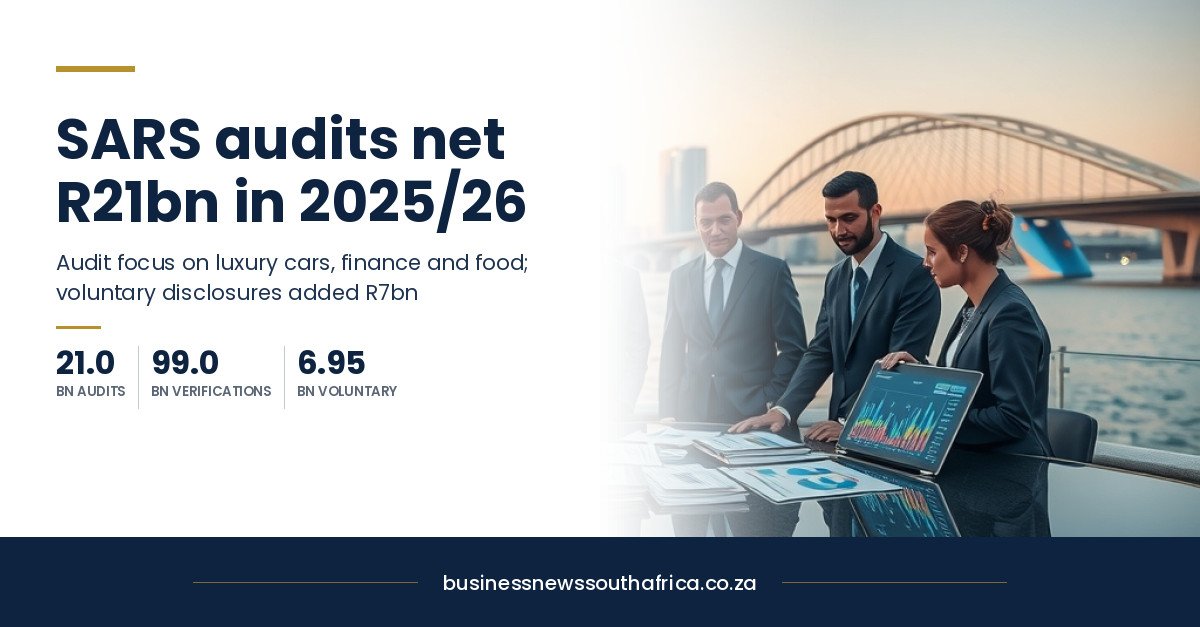
SARS audits delivered R21.0 billion in revenue in 2025/26, excluding penalties and interest, according to the Revenue Service’s 2025/26 annual report. The report, which SARS announced on its news page, also shows where the audit effort went and how much came in through the voluntary disclosure programme. For a business, the report is a useful read on what SARS looks for and on the route it offers for putting past mistakes right before an audit starts.
What the audits recovered
In its enforcement section, SARS reports revenue results of R21.0 billion from audits, made up of R8.9 billion in cash collections and R12.1 billion that it labels “leakage prevention”. It completed 1,390 in-depth cases and 1,004 standard cases. SARS gives a success rate of 94% for in-depth cases and 80% for standard cases, and the page does not define the term.
Separately, SARS says revenue from verification enforcement interventions was approximately R99.0 billion, compared with R95 billion in the prior period. It names VAT (R56.5 billion) and personal income tax (R17.5 billion) as the strongest products and credits improved rules in its risk engine for better case selection.
The four audit focus areas it highlights
- Financial Intelligence Centre: 101 cases, R4.3 billion.
- Lifestyle and luxury vehicles: 185 cases, R2.3 billion.
- Security sector: 91 cases, R4.4 billion.
- Withholding taxes on visiting artists: 1,294 cases, R167.2 million.
The report describes its specialised audits as complex, integrated and in-depth audits in the small, medium and micro enterprise sector that focus on taxpayers and traders who intentionally choose not to comply, with a low volume of cases and high impact. It says forensic methods use internal and third-party data, with support from its Electronic Forensic Services team.
The risks SARS says it profiled
The report lists the risks SARS investigated and profiled during the year: fuel, tobacco, alcohol, clothing and textiles, leather and footwear, VAT carousel fraud in the gold sector, phoenixism, abusive liquidation and business-rescue practices, illicit financial flows and tax evasion. It says these matters typically involve complex structures meant to hide liabilities or exploit weaknesses in trade and financial systems, and that SARS combines machine learning with expert oversight. SARS says its compliance philosophy is that most taxpayers are willing to comply with the least effort and cost, and that its response ranges from reminders and verifications to in-depth audits and criminal investigations.
Voluntary disclosure: what it recovered
The Voluntary Disclosure Programme (VDP) lets taxpayers come forward to regularise past non-compliance. SARS says it encourages taxpayers to approach the VDP unit before any enforcement action starts, to avoid possible disqualification. For 2025/26 the report says SARS:
- received 1,852 new VDP applications and processed 1,883;
- entered into VDP agreements worth R5.76 billion;
- collected R6.95 billion, made up of R5.5 billion in cash and R1.5 billion non-cash;
- approved 54 deferment of payment applications linked to VDP, amounting to R513.7 million; and
- issued 240 non-binding private opinions to help taxpayers rectify past non-compliance on a no-name basis.
VAT accounted for 56.60% of the value of VDP disclosures and income tax, company and personal, including local and offshore, for 23.80%. SARS says its media alerts on trusts, cryptocurrencies and electronic service suppliers have been effective: it received 63 new crypto-related applications and finalised 72 cases, with agreements worth R88.3 million, and received 86 new applications from trusts and trust beneficiaries and finalised 94, worth R80.6 million.
What business owners can take from it
- VAT is where the money is. It is the largest source of both verification yield and voluntary disclosures, so VAT returns and supporting records are the first place to check.
- Company structures are in view. Phoenixism, abusive liquidations and business-rescue practices are on the list of profiled risks.
- Disclosing early is a recognised route. SARS says to come forward before enforcement action begins, and offers no-name private opinions for taxpayers who want to test their position first. A registered tax practitioner can say whether VDP fits your case.
- Corrections are possible. If you find an honest mistake in a return, SARS’s new Interpretation Note 147 sets out when a reduced assessment is available.
For how SARS uses outside data in checks, see our explainer on how SARS checks your bank deposits, and for how the Revenue Service’s collections are tracking this year, our report on SARS refunds and the R2.144tn collection forecast.
All figures are from SARS’s 2025/26 annual report and are the Revenue Service’s own. This article is general information, not tax advice.