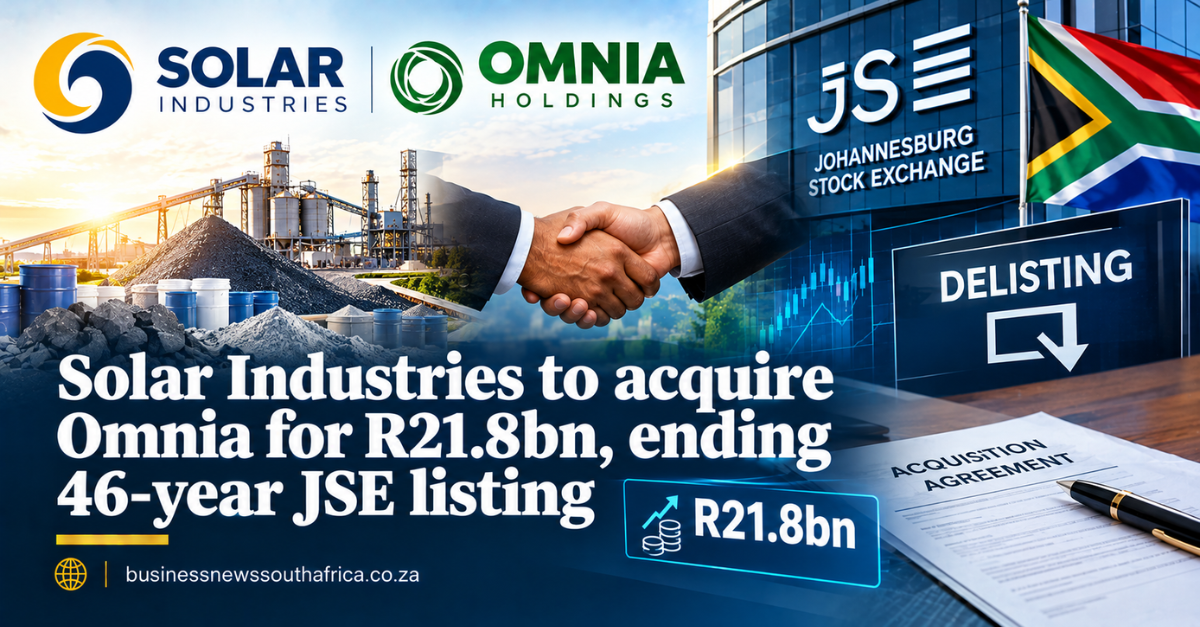
On 14 September Omnia and India-based Solar Industries issued a joint statement confirming that Solar Industries intends to buy all of Omnia’s issued ordinary shares for R134.50 each, a 14.3% premium to the closing price on the previous Friday. The transaction, valued at R21.8 billion, would also see Omnia removed from the Johannesburg Stock Exchange (JSE) where it has been listed since 1980, and from the secondary market A2X.
For the owners of small farms, local mining contractors and other businesses that rely on explosives and fertiliser, the deal signals a change in who controls a key domestic supplier. Omnia supplies explosives to South Africa’s mining sector and fertilisers to its agricultural sector, and also runs a smaller chemical manufacturing arm. If the acquisition goes through, those customers could see new product lines, technology upgrades and possibly different pricing, depending on how Solar integrates the business.
Solar Industries, founded in 1995 by Indian billionaire Satyanarayan Nuwal, is the largest manufacturer and exporter of industrial explosives in India. Its market capitalisation is roughly ₹2.02 trillion (about R343.5 billion) and its share price has risen about 80% over the past year. The company already owns Problast BS, a mining explosives firm, and operates in Ghana, Nigeria, Tanzania and Zambia. Adding Omnia would give Solar a foothold in Canada, Australia, Brazil and Indonesia, extending its reach across four continents.
Omnia’s chief executive Seelan Gobalsamy told reporters the deal is about “accelerating growth to put balance sheets together”. He said Solar’s expertise in drones and autonomous robotics could support Omnia’s mining and agricultural operations, and that Solar’s strong position in India could help grow Omnia’s agri-business in Australia and elsewhere. Those comments are company statements and have not been independently verified.
The acquisition still requires approval from South African regulators and a vote by Omnia shareholders. The parties have set a long-stop date of 31 July 2027, the latest date by which all conditions must be satisfied or the agreement expires. Until those approvals are granted, the transaction remains a proposal.
Why the timing matters
Omnia reported a 6% rise in revenue to R24 billion and a 28% jump in operating profit for the last financial year. Those figures show a healthy business, but the company also flagged pressure from the war in the Middle East, which has disrupted the Strait of Hormuz. The disruption has driven up costs for nitrogen-based feedstocks used in fertilisers and has made supply chains less reliable. Omnia warned that those pressures have added volatility to input costs and complicated capital planning.
For South African SMEs that buy fertiliser or explosives, higher input costs can translate into higher prices at the point of sale. If Solar can bring in cheaper raw material sources or more efficient production methods, the downstream effect could be lower costs for local users. Conversely, a change in ownership could also mean a reassessment of credit terms or delivery schedules, which smaller buyers will need to monitor.
From a broader industry perspective, the deal reflects a growing trend of Indian firms expanding into Africa’s mining supply chain. While the source does not name other recent acquisitions, Solar’s existing presence in several African countries suggests it is pursuing a continent-wide strategy. That strategy may increase competition for local suppliers and could push South African firms to adopt newer technologies to stay competitive.
Investors in Omnia saw the share price rise as much as 7.5% on Monday after the announcement, settling at a 4.2% gain at 9:20 a.m. local time, which gave the company a market value of about R19.8 billion. The premium paid by Solar therefore represents a modest uplift over the current market price, but the real value to shareholders will depend on whether the deal clears regulatory hurdles and delivers the promised synergies.
In summary, the proposed acquisition could reshape the supply landscape for South Africa’s mining and agricultural inputs. Small-scale users should watch for any changes in product availability, pricing and service terms once the deal is finalised. The transaction also illustrates how global players are looking to South Africa’s resource-intensive sectors as part of a wider diversification effort.