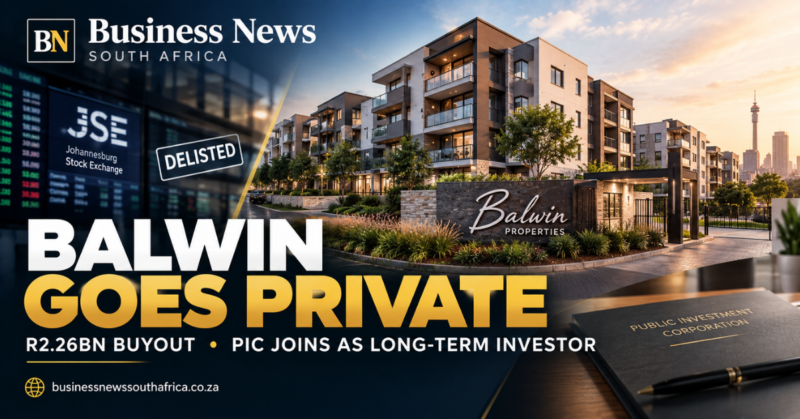
Balwin Properties announced that it will no longer be listed on the Johannesburg Stock Exchange (JSE), according to the company’s statement on the Moneyweb podcast. The delisting means the firm will move from a public share-trading platform to a private ownership structure, a shift that can affect how it raises capital and reports to investors.
For small-to-medium property developers, the move is a reminder that public listing is not the only route to growth. A listed company must meet continuous disclosure rules, the requirement to publish material information promptly, and adhere to JSE governance standards. Once private, a developer can negotiate funding directly with banks or private investors, but it also loses the liquidity that a public share market provides.
The National Business Credit Rating Financial Limited (NBCRFLI) used the same podcast to respond to questions about its own financial management. The regulator-linked rating agency said it had addressed all outstanding concerns and that its current rating methodology remains robust. NBCRFLI’s statement is a claim by the agency; independent verification of its internal controls has not been published.
Balwin’s decision comes as the South African property market grapples with higher borrowing costs and a slowdown in commercial leasing. Developers who rely on bank loans may find tighter credit conditions, while those with strong equity bases can still access private equity. The company’s future plans were not detailed, but the shift suggests a focus on restructuring its balance sheet away from public market pressures.
Regulatory framework that governs a JSE listing
The JSE operates under a comprehensive regulatory framework that aligns with the Companies Act and the Financial Markets Act. Listed entities are required to submit periodic financial statements, including half-year and annual reports, to the exchange and to the Companies and Intellectual Property Commission. In addition, they must maintain a board of directors that meets independence criteria, establish audit and remuneration committees, and disclose any material events that could influence share price within a prescribed time frame. Failure to comply can result in penalties, suspension of trading, or forced delisting.
Continuous disclosure is a cornerstone of the regime. When a listed company becomes aware of information that could affect an investor’s decision , such as a major contract, a change in senior management, or a significant legal dispute , it must inform the market promptly. This requirement is intended to promote fairness and to prevent insider trading. For a private company, the same level of public reporting is not mandatory, which can reduce administrative burden but also limits the amount of information available to potential investors.
Why delisting matters to South African business owners
For owners of small-to-medium enterprises (SMEs) in the property sector, the decision to delist carries several practical implications. First, the removal from the exchange eliminates the need to maintain a public investor relations function, which can be costly for firms with limited resources. Second, the company no longer has to meet the JSE’s strict corporate governance codes, allowing more flexibility in board composition and decision-making processes. Third, the firm must secure capital through alternative channels, such as private placements, direct negotiations with lenders, or partnerships with institutional investors.
While private financing can be faster and more tailored, it often comes with higher cost of capital because lenders demand a premium for the reduced transparency and liquidity. Conversely, a public listing provides access to a broad pool of capital through the equity market, but it also subjects the company to market volatility and the pressure of quarterly performance reporting. Business owners need to weigh these trade-offs in light of their growth strategy, risk appetite, and the competitive dynamics of the property market.
How delisting is carried out in practice
The JSE has a formal delisting procedure that begins with a proposal from the company’s board. Shareholder approval is required, typically through a special resolution passed at a general meeting. The company must also appoint a qualified delisting adviser, who assists in preparing the necessary documentation, communicating with shareholders, and ensuring compliance with the exchange’s timeline. Once the resolution is passed, the JSE publishes a notice of intention to delist, and the company must settle any outstanding obligations, such as clearing pending orders and addressing any shareholder grievances.
After the delisting is completed, the company’s shares are removed from the official trading platform. Existing shareholders may be offered the option to sell their shares back to the company at a fair price, or they may retain their holdings as unlisted securities, which can be traded over the counter if a market exists. The transition also triggers changes in reporting obligations: the firm must still file annual returns with the Companies and Intellectual Property Commission, but it is no longer required to publish those documents on the JSE website.
Implications for financing in the property sector
The property development industry in South Africa relies heavily on a mix of equity and debt. Bank financing remains the dominant source of debt, but banks have become more cautious in response to macro-economic pressures, such as inflation and currency volatility. In this environment, developers with strong balance sheets and clear project pipelines can still attract private equity, mezzanine financing, or joint-venture partners. The delisting of Balwin Properties may signal a strategic pivot toward these alternative sources, allowing the firm to negotiate terms that are more aligned with its long-term objectives.
For developers that continue to operate as listed entities, the ability to raise equity through rights issues or secondary offerings provides a valuable buffer against tightening credit conditions. However, the cost of issuing new shares can be significant, and dilution of existing shareholders must be managed carefully. Private funding, by contrast, often involves fewer shareholders and can be structured to protect existing ownership, but it may require the provision of collateral or higher interest rates.
Role of rating agencies in a private environment
Rating agencies such as NBCRFLI play a crucial role in assessing the creditworthiness of both listed and private companies. Their methodologies typically evaluate financial performance, governance practices, industry outlook, and management quality. While NBCRFLI’s statement on the podcast affirmed the robustness of its rating approach, the absence of publicly available verification means that private firms must rely on the agency’s reputation and the transparency of their own disclosures to maintain confidence among lenders and investors.
In a private setting, developers may choose to commission an independent credit assessment to demonstrate their financial health to potential financiers. Such assessments can be shared with banks, private equity firms, or strategic partners, providing an objective benchmark that compensates for the reduced public scrutiny that accompanies delisting.
Broader market context and related developments
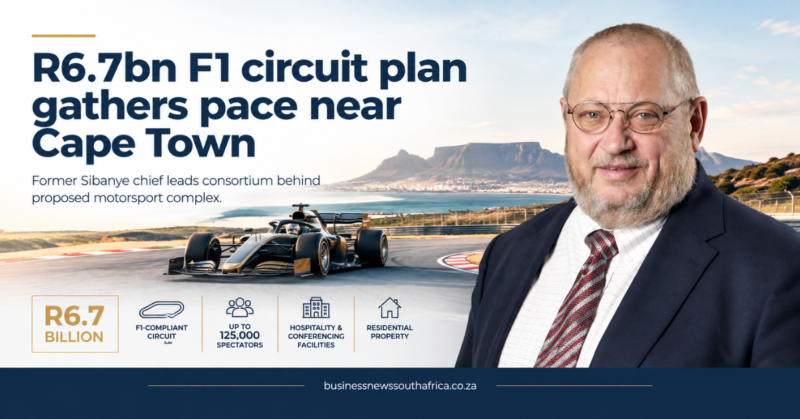
In a separate segment, Blue Mountain Racing announced a R6.7bn investment in a new “destination” development for Formula 1, acquiring 600 hectares of land near Cape Town. While the project is unrelated to Balwin’s property activities, it highlights the growing interest in large-scale sport-driven tourism projects and the potential for private capital to fund ambitious infrastructure. This example underscores a broader trend in which private investors are increasingly willing to commit substantial resources to projects that promise diversified revenue streams and long-term economic impact.
The podcast also touched on education, asking who should prepare graduates for the local economy. Eduvos, a private education provider, argued that industry-specific training is essential for closing the skills gap, a point that resonates with property firms seeking staff skilled in project finance and construction management. A well-trained workforce can improve operational efficiency, reduce project delays, and enhance the overall attractiveness of a development to lenders and investors.
Takeaways for SME developers
Overall, Balwin’s exit from the JSE underscores the trade-off between public transparency and private flexibility. SME developers will need to weigh the benefits of easier access to capital against the loss of market visibility when considering a similar path. Key considerations include the ability to meet ongoing governance and disclosure obligations, the cost and availability of alternative financing, and the strategic importance of maintaining a public profile for brand building and stakeholder confidence.
Developers that choose to remain listed should continue to monitor regulatory updates, maintain robust investor relations, and explore hybrid financing structures that combine equity and debt. Those that move to a private model must invest in strong internal controls, transparent reporting to lenders, and proactive engagement with rating agencies to sustain credibility in the market.
In either scenario, the underlying principle remains the same: a clear understanding of the regulatory environment, a disciplined approach to financial management, and a strategic alignment of capital structure with long-term business goals are essential for success in South Africa’s dynamic property sector.