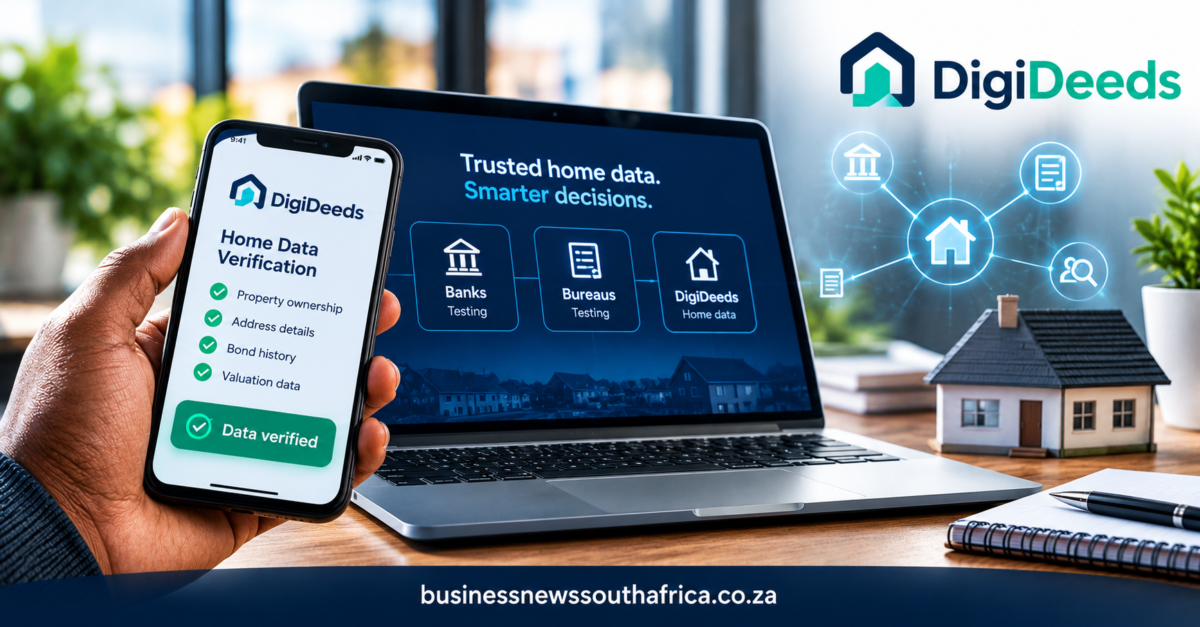
DigiDeeds, a start-up founded by a former Capitec credit executive, says it is selling data on homes outside South Africa’s title-deed system to banks and credit bureaus, and that three of the largest banks and three of the main credit bureaus have bought it so far to test it. The claims come from chief executive Jaco Carstens in an interview with TechCentral published on 26 October 2026, and none of the buyers has been named.
What it means for your business: if you lend, insure, sell on credit or verify customers, a new source of proof-of-address and “alternative” data for people without title deeds could widen your market. It also comes with open questions about accuracy, consent and security, and the company’s strongest claims have not been independently checked.
The gap DigiDeeds says it fills
Citing the Centre for Affordable Housing Finance in Africa’s 2024 yearbook, DigiDeeds says only 6.9 million of South Africa’s 17.8 million homes have a title deed, and estimates that more than 35 million people live in informal and RDP homes, backyard rooms and rural homes on communal land. Its own website calls the 35 million figure a DigiDeeds estimate. We could not confirm the housing figures against the yearbook itself.
For these households, proof of address is a practical problem. An EWN report from February 2026 quotes an attorney saying no single Act sets out what counts as proof of residence, so each institution sets its own rules, and that people in informal settlements may need an affidavit from a neighbour or ward councillor.
How a DigiDeed is created
The app launched in March 2026 and is free for members. According to TechCentral and the company’s own how-it-works page, the steps are:
- The member takes a selfie and photographs an ID or passport; for an ID, the app reads the barcode.
- They drop a pin on their home and photograph it, and the location is checked against GPS and geographic information system (GIS) mapping.
- Seven neighbours confirm the address and whether the person owns, rents or simply lives in the home.
The result is a digital certificate that serves as proof of address and, for an owner, records ownership of the structure, but not the land under it. DigiDeeds works only in established townships. “If somebody is staying illegally on land, that’s not where we serve,” Carstens told TechCentral.
How the company makes money
DigiDeeds says it buys some GIS data, enriches it with what members and their neighbours supply, and sells the result to credit bureaus, which Carstens calls the wholesalers, and to banks, the retailers. The company’s client page lists three ways to buy: real-time API calls, pay-per-report, and a monthly licence for higher volumes. It lists uses such as address verification and credit scoring for people with thin or no credit files.
Numbers that do not match
The figures differ between sources, so treat all of them as company claims:
- Members: TechCentral reports more than 6 600; the company website says more than 5 200 since the March launch.
- Neighbour confirmations: more than 40 000 according to TechCentral; more than 42 100 on the website.
- Data points: TechCentral says each member generates 26 data points, from which 11 features were derived for credit models. The website says it holds 37 data points per member, 26 verified and 11 worked out from those, such as fraud scores.
The claims to test before you rely on it
Collateral. Carstens says a DigiDeed can be pledged to a lender as security through cession, giving households collateral they have never had. DigiDeeds says it holds an advocate’s opinion that the approach is consistent with existing law. Asked whether a DigiDeed has legal standing, Carstens pointed to Roman law: “If seven Romans say so, it is so.” We have not seen the opinion, and TechCentral does not report that a bank has accepted a DigiDeed as security.
Economic impact. Carstens told TechCentral he had not done his own research on the value that could be unlocked, but believes that if banks and other institutions embrace the model it could double South Africa’s economic growth rate. That is a projection, not a finding.
Data protection. A database of IDs, selfies, home photographs and GPS co-ordinates for low-income households is an obvious target, TechCentral notes. DigiDeeds says the platform was built by Stellenbosch software group Octoco and its subsidiary Polymorph on the Neo4j graph database, that Carstens is registered as information officer under the Protection of Personal Information Act (POPIA), and that members consent to the use of their data. “As soon as one becomes the softest target, you will be attacked,” Carstens said.
The company behind it
DigiDeeds was incorporated in November 2024 and says it has more than 100 investors. Carstens, a chartered accountant, spent 20 years as a credit executive at Capitec. Chairman Ruben Richards and non-executive directors Charles Robertson, Ian Abrahams and Marcus Courage complete the board, according to TechCentral. The company is aiming for 125 000 members within 12 months and says it needs 500 000 to comfortably reach breakeven.
What to do
- Lenders and insurers: ask for a pilot, test the data against your own repayment history, and get legal advice before treating a DigiDeed as security.
- Businesses doing KYC: check whether your compliance team will accept the record as proof of address under your own policy, since rules vary by institution.
Related reading: our explainer on South Africa’s digital identity system and our report on TechCabal’s view that the funding gap may be a data issue.